Who’s Coordinating Your Retirement Plan?
Most successful people don’t have a shortage of financial professionals.
They may have a financial advisor managing investments, a CPA preparing taxes, an attorney handling estate documents, and perhaps an insurance or Medicare specialist.
On the surface, that can feel like everything is covered.
But there is an important question:
Who is making sure all of those pieces actually work together?
Having good professionals is not the same thing as having a coordinated retirement plan.
Retirement Decisions Overlap
A retirement decision rarely affects just one area.
A tax decision can affect Medicare premiums.
An investment decision can affect taxes and retirement income.
An estate-planning decision can conflict with beneficiary designations.
A withdrawal decision can affect future required minimum distributions, taxes, and what eventually passes to your family.
That is why retirement planning works best as an integrated system rather than a collection of separate decisions.
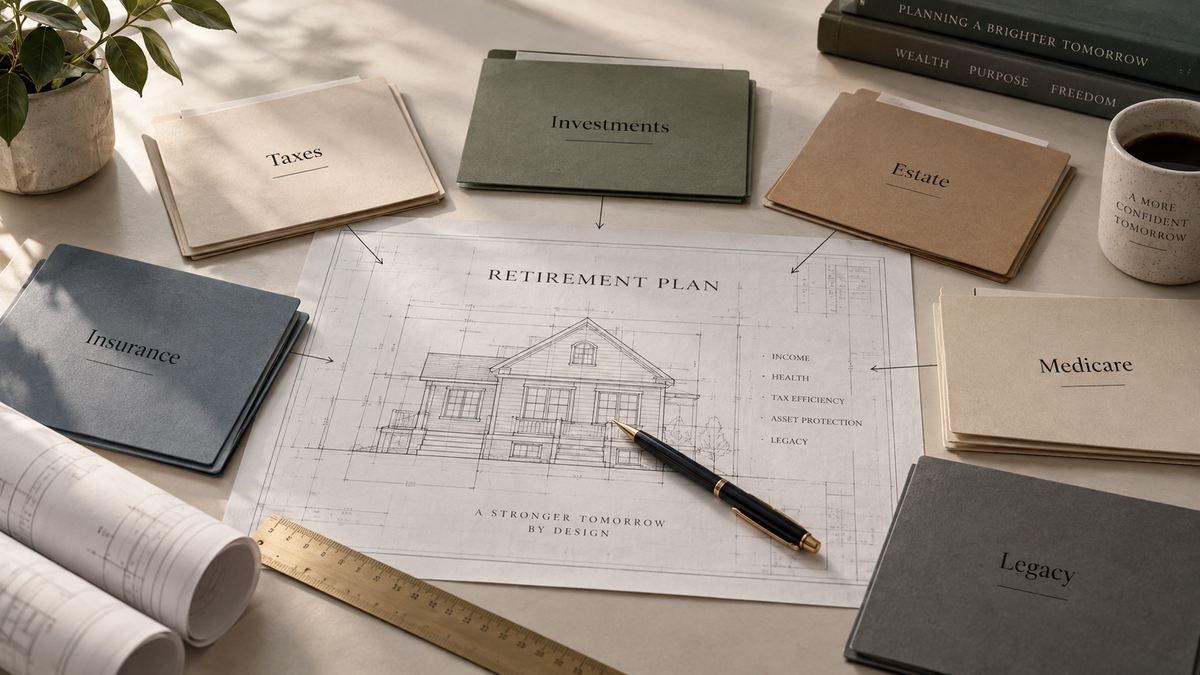
Think of Your Financial Life Like a House
Imagine building a house.
You may have an excellent electrician, plumber, carpenter and roofer.
But somebody still needs to look at the blueprints and make sure everyone is building the same house.
Otherwise, you can have excellent individual work and still end up with problems where the pieces meet.
Your financial life works the same way.
Someone needs to be asking:
What else does this decision affect?
If we make a tax move, what does it do to Medicare?
If we change an investment, what does it do to taxable income?
If we update the trust, do the beneficiaries and account ownership still line up?
Those are coordination questions.
Having the Pieces Is Not Enough
Many people can check the boxes.
“I have an advisor.”
“I have a trust.”
“My CPA handles my taxes.”
That is a good start.
But the better question is whether each piece is current, appropriate, effective, and coordinated with everything else.
A trust can exist and still not be properly funded.
An investment portfolio can be diversified and still take more risk than necessary.
A tax return can be prepared correctly without anyone looking at how today’s decisions may affect taxes 10 or 20 years from now.
The Question to Ask
As retirement approaches, coordination becomes even more important.
You are no longer simply trying to accumulate wealth. You are deciding how to turn what you have built into income, security, flexibility, lifestyle and legacy.
So ask yourself:
Who is responsible for looking at the entire picture?
If the answer is “I’m not really sure,” that does not necessarily mean something is wrong.
It may simply mean there is an opportunity to make your financial life more coordinated.
The question is not just whether you have all the pieces.
It is whether those pieces are working together to help you Retire on Your Terms.