A Collection of Accounts Is Not a Retirement Plan
Most people approaching retirement have accumulated a variety of financial pieces over the years.
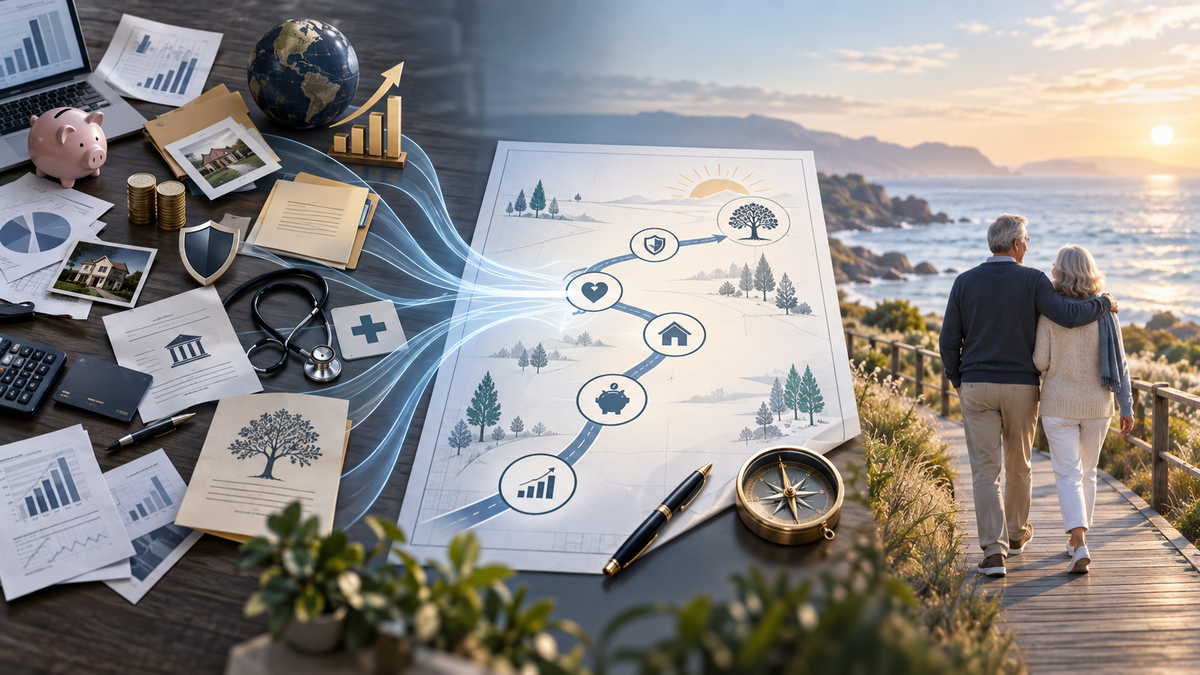
They may have a 401(k), IRAs, brokerage accounts, Social Security, insurance policies, a will or trust, and relationships with a CPA, attorney, or financial advisor.
But having all of those pieces does not necessarily mean you have a coordinated retirement plan.
A true retirement plan should answer a much bigger question:
How do all of these pieces work together to help you live the retirement you want?
That means looking beyond investment performance alone.
For example, the way your investments are structured can affect your taxes. The income you take from retirement accounts can affect Medicare premiums. Roth conversions may reduce future required distributions but create additional taxes today. Beneficiary designations need to coordinate with your estate documents. And decisions about Social Security, pensions, and portfolio withdrawals all affect how much dependable income you have throughout retirement.
Each decision can influence several others.
That is why retirement planning should not happen in separate silos.
We believe the starting point should be the life you want to live. From there, your income, investments, taxes, healthcare, estate planning, risk management, and legacy should all be coordinated around that vision.
As retirement approaches, it may be worth asking yourself:
Do I have a collection of financial accounts and professionals—or do I have one coordinated plan?
The difference can have a meaningful impact on your confidence, your taxes, your family, and ultimately your ability to retire on your terms.